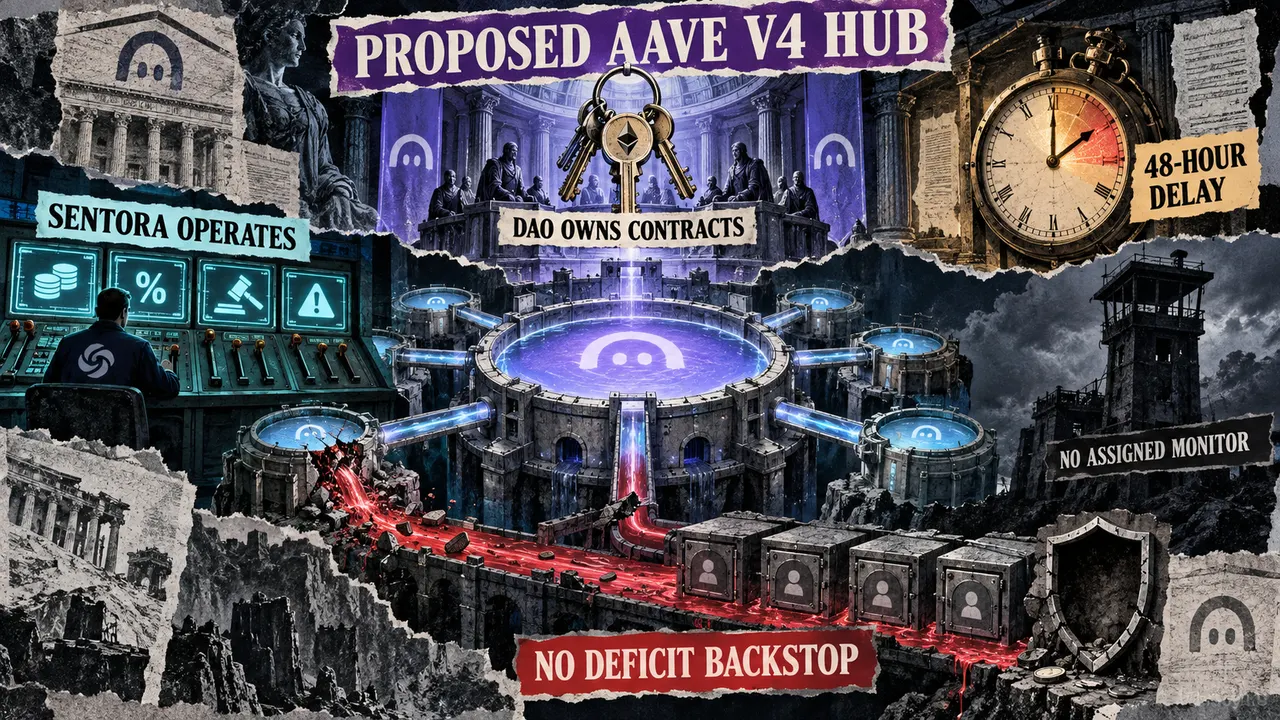
Aave DAO would own the contracts for a proposed Ethereum lending market, but Sentora would make the day-to-day decisions that shape its credit risk.
In a governance proposal posted Sept. 28, the DeFi risk manager asks to operate an isolated Aave V4 Hub and its lending Spokes through revocable roles. The split puts an immediate risk response in Sentora’s hands and leaves the DAO with ownership, a review path for new markets and the power to withdraw those roles.
Sentora would choose its collateral, interest-rate curves, liquidation settings, and oracles. Aave’s existing risk service providers would have no assignment to monitor the instance, recommend changes, or respond to incidents.
The proposal is still an ARFC for community discussion, and the next steps include a Snapshot vote followed by an on-chain Aave Improvement Proposal before any approval.
Who can act, and when
Aave V4 separates the Hub that holds liquidity from the Spokes where loans originate against collateral. Sentora proposes one Ethereum Hub for its Spokes, with no credit lines to or from other Aave DAO Hubs, and its own Spokes would still draw from suppliers in Sentora’s Hub.
The proposal limits borrowable assets to RLUSD, PYUSD, and OUSD, excluding USDC and USDT.
Under the plan, the DAO’s Governance Short Executor would retain the admin roles over the Hub, Spokes, and AccessManager. The DAO would retain contract upgrades and role grants, and Sentora would own none of the contracts.
Instead, it would receive operational roles to manage the markets, and the DAO could revoke those grants through an on-chain governance proposal.
Those roles create different response times:
Proposed action
Who acts
When
DAO recourse
Pause or freeze a reserve, halt an asset or Spoke
Sentora operational address
Immediately through a restrictive role
Revoke Sentora’s roles through governance
Reduce a collateral factor or tighten a cap
Sentora through a one-way Risk Steward
Immediately
Revoke Sentora’s roles through governance
Increase risk, or change a rate model or liquidation configuration
Sentora operational address
After a 48-hour on-chain delay
Observe the scheduled change and pursue role revocation; no individual cancellation power is specified
Add collateral or deploy another Hub
Sentora proposes; an appointed DAO service provider may object
Two-week forum review before scheduling or deployment
An objection pauses the action for a binding Snapshot vote
The 48-hour delay applies to risk increases and to functions whose direction is ambiguous, including rate models and liquidation configurations. The proposal sets no limit on the size of an increase and no cooldown between updates.
The delay makes a scheduled action visible, but the DAO would have no mechanism to cancel that one action inside the window. Revoking Sentora’s roles would require a separate on-chain governance proposal and would remove its authority going forward.
For a new Hub or collateral asset, Sentora would post an analysis and wait two weeks. An objection from any appointed Aave DAO service provider would stop the rollout and send it to a binding Snapshot vote.
The same proposal says no service provider is scoped or compensated to review these submissions. It also excludes the instance from the providers’ monitoring, parameter-recommendation, and incident-response mandates.
Providers could raise concerns on their own initiative, but a quiet review window would not establish that anyone examined the change. The proposed veto depends on someone noticing a problem and choosing to object.
Sentora CEO Anthony DeMartino argued in a November 2025 essay that risk management needs measurable controls and continuous monitoring. The new proposal would assign that operating role to Sentora, while leaving the DAO’s providers free to speak up without requiring them to watch the market.
Who absorbs a shortfall?
If a liquidation exhausts a borrower’s collateral while debt remains, the Spoke reports the shortfall to the Hub from which it drew the debt asset. The Hub records the deficit against that asset, and TokenLogic’s V4 Umbrella proposal says suppliers of that Hub asset bear the loss.
A separate ledger identifies the Spoke that originated it, and the absence of cross-Hub credit lines would prevent a direct draw on other DAO Hubs for this instance’s loans. It would not shield suppliers inside Sentora’s Hub from its own Spokes.
[](https://cryptoslate.com/wp-content/uploads/2026/09/exec-0ba7d5bf-ab70-4229-9d04-23e541cd005b.png)Sentora would manage day-to-day risk while Aave DAO retains oversight, but the proposal names no deficit backstop.
The proposed commercial bargain gives 50% of the instance’s protocol revenue to Sentora and 50% to the DAO, including reserve-factor earnings and protocol liquidation fees.
Aave’s separate V4 Umbrella ARFC proposes deficit offsets and staked coverage for Core WETH, Core USDC, and Core USDT. Its coverage does not name Sentora’s proposed Hub, and Sentora’s ARFC specifies no Umbrella market, deficit offset, or Sentora-funded first-loss layer for it.
A future proposal could address that gap, but a lender cannot infer protection from the DAO’s contract ownership or its fee share.
Sentora’s narrative says USDe and PST would back the first RLUSD yield loans, with PRIME and mWIN added later, while its specification lists all four. Its Bluechip description names RLUSD borrowing against kBTC, but the table lists RLUSD, PYUSD and OUSD.
The OUSD oracle is also left to be confirmed before launch. The final asset and price-feed choices would help define the risk borne by suppliers.
For the DAO, the decision before any Snapshot or AIP is whether to grant these operating rights with no assigned independent watcher and no stated first-loss protection for the isolated Hub.
For prospective suppliers, the final asset list, oracle choices, and any explicit deficit coverage will determine how much risk sits behind those DAO-held contract keys.